Following a rebound in confidence at the end of 2025, the European office market stalled in Q1 2026. In a context of economic and geopolitical uncertainty, take-up declined by 16% year-on-year, driven by a slowdown in large transactions, while investment volumes fell by 13%. The start of the year has been marked by caution, with both occupiers and investors adopting a more selective approach.
Leasing activity slows in Q1 2026
In the first quarter of 2026, leasing activity across Europe declined by 16%. Total take-up reached 1.67 million sqm across the 18 main European markets*, significantly below the five-year average (-16%). This contraction is primarily due to a drop in transactions above 5,000 sqm across many markets.
In an uncertain economic and financial environment, occupiers are taking a more cautious stance, with a growing preference for smaller spaces and higher-quality buildings.
Take-up declined in Paris and London (-23% and -15% respectively). The six main German markets followed a similar trend, with an overall decrease of 12%, although performances vary between cities. Munich stood out, with take-up reaching 172,000 sqm in Q1 (+26% year-on-year), its highest quarterly level since 2022, supported by three transactions above 20,000 sqm. Berlin also performed strongly, with 146,000 sqm transacted, up 42% year-on-year.
Elsewhere in Europe, trends remained mixed: Milan and Madrid recorded significant declines (-36% and -25%), while Barcelona (+34%), Dublin (+21%), Rome (+11%) and Brussels (+11%) posted growth, highlighting a heterogeneous recovery across markets.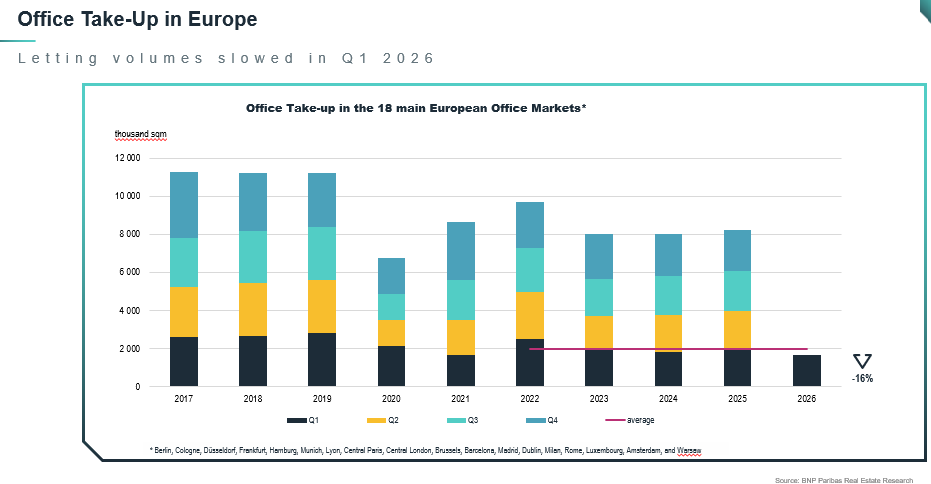
Download the press release for more insights
Read on about the evolution of the vacancy-rate, the prime rents and disparities across Europe.

